


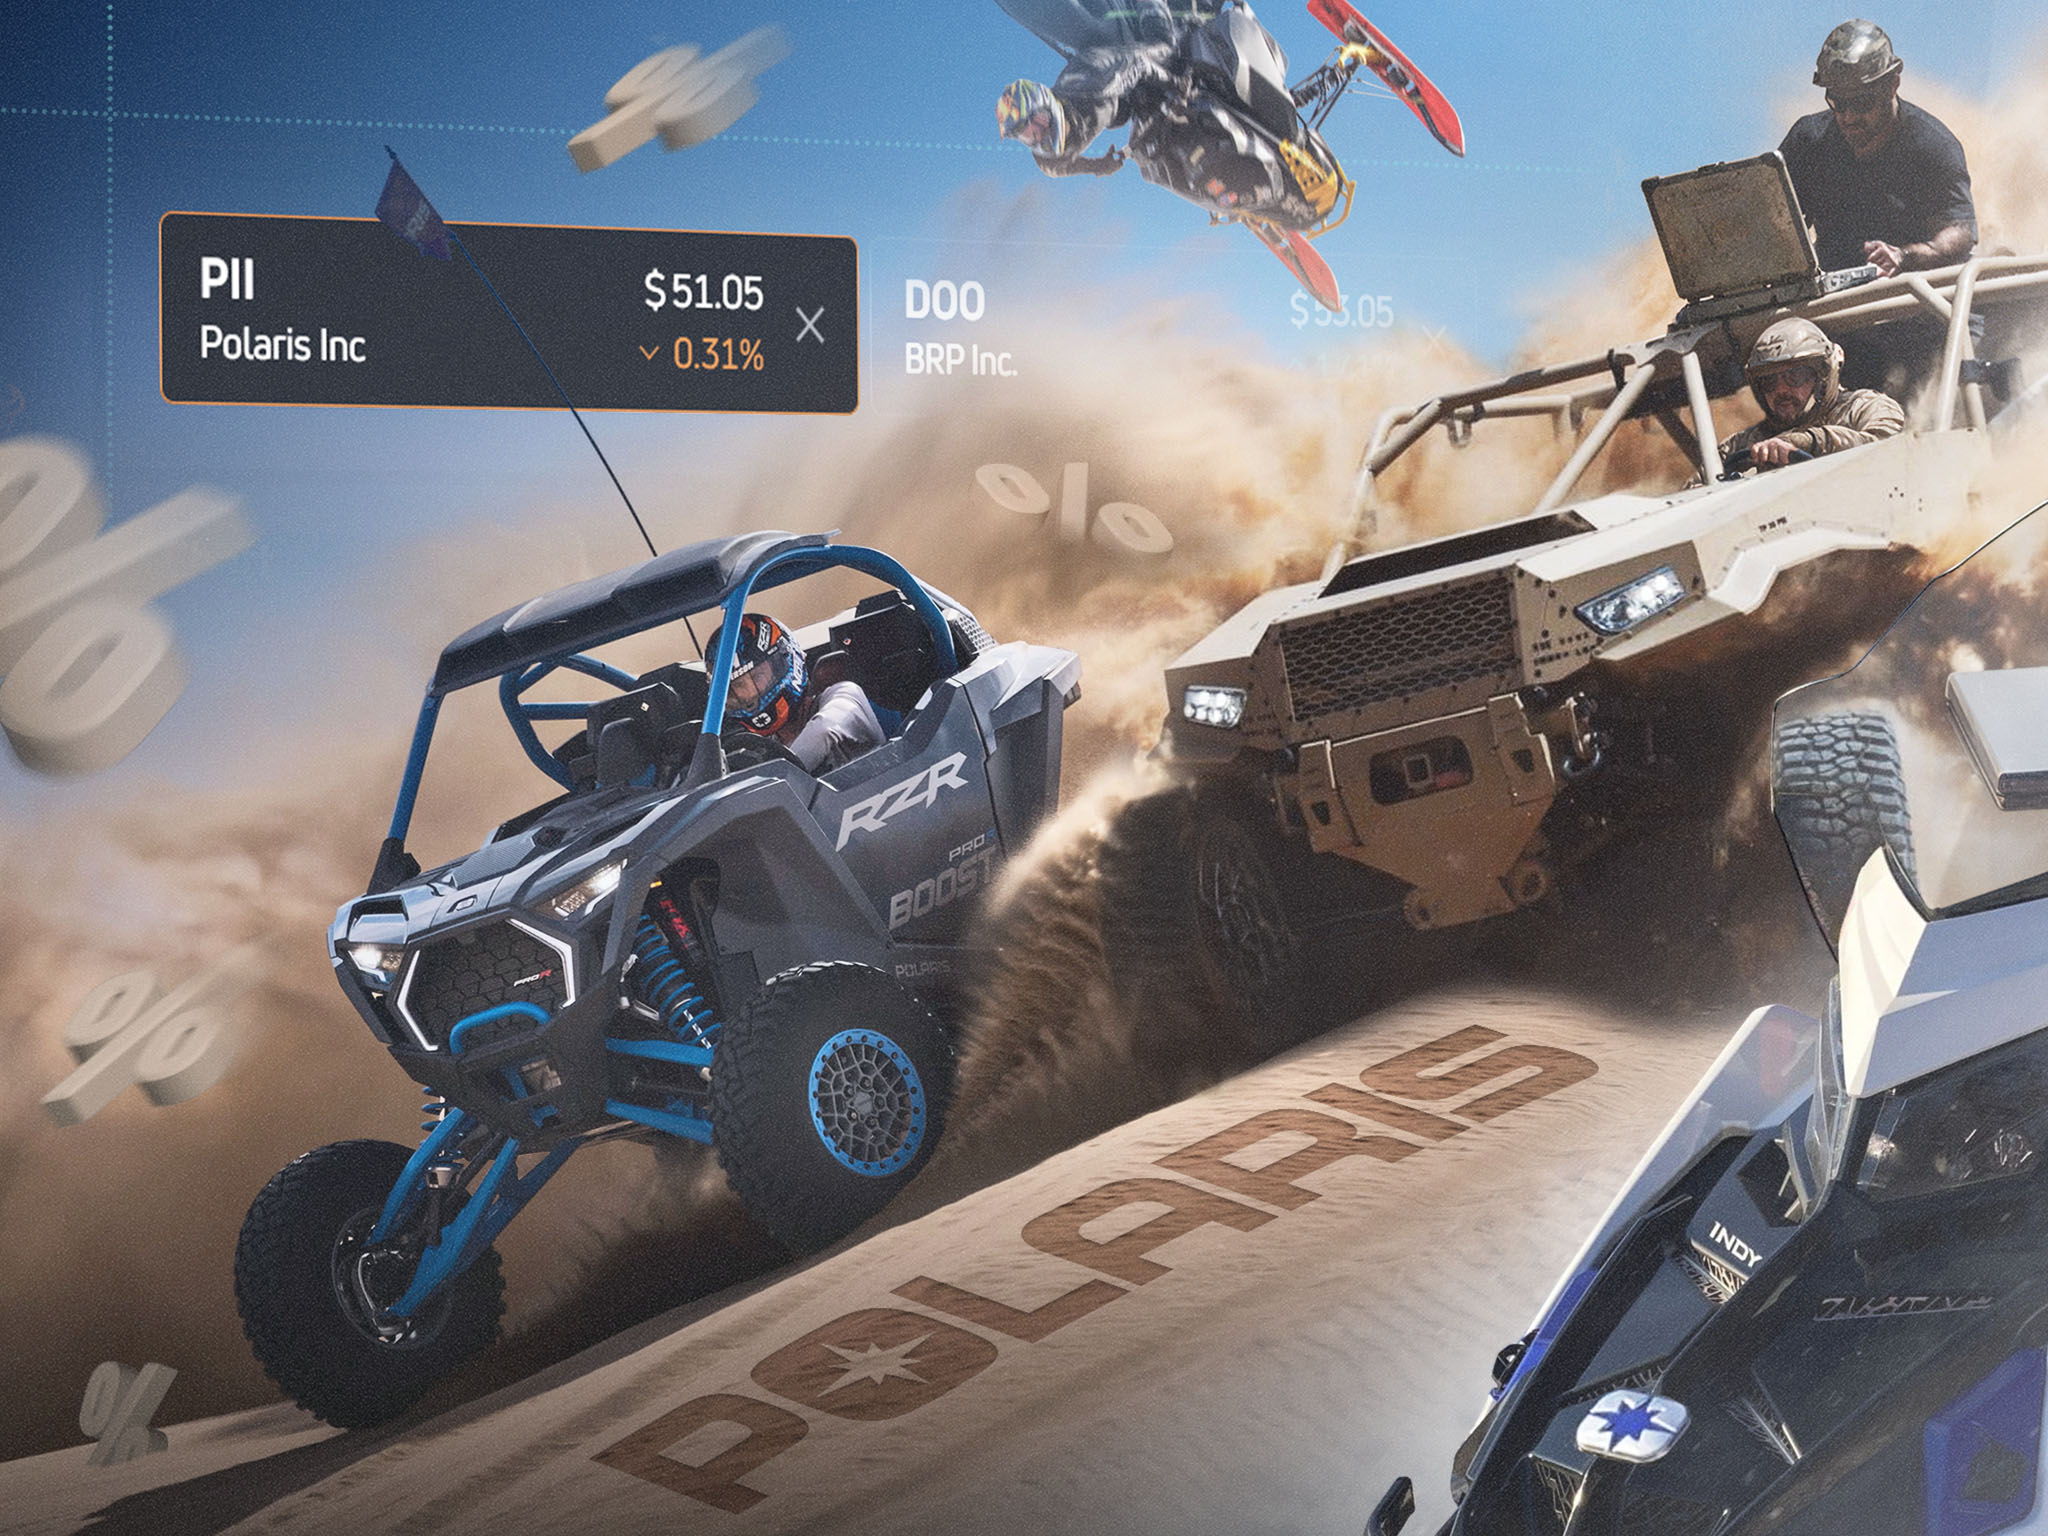

The powersports industry, which includes all-terrain vehicles and snowmobiles, likely makes you think more about participation than investing.
But there are some strong companies in the space, such as 72-year-old Polaris (NYSE: PII). In addition to ATVs and snowmobiles, it supplies on-road vehicles, such as three-wheelers; boats; and defense and commercial vehicles. Snowmobiles were its initial flagship product, and it expanded from there. Analysts hold the corporation in high regard.
“Polaris is one of the longest-operating brands in powersports,” Morningstar analyst Jaime Katz wrote in a report. “Its brands, innovative products, and lean manufacturing underlie the firm’s wide economic moat.”
It benefits from strong research and development, high product-quality, operational excellence, and a sharp acquisition strategy. That has enabled Polaris to “build a recreational and utility vehicle powerhouse,” she said. It has one of the top U.S. market share in various products.
The company has three divisions: Powersports, which includes ATVs and snowmobiles; Marine, which of course is boats; and Aixam, a leader in the European quadricycle market, & Goupil, which makes electric compact utility trucks.
Powersports dominates
Powersports accounted for 85% of Polaris revenue in the second quarter, Marine for 9% and Aixam & Goupil for 4%. (The rest comes from Corporate). Almost 3,000 dealerships sell Polaris vehicles around the world, with 87% of second-quarter sales coming in North America.
Research and development have allowed Polaris to develop “a pipeline of compelling new products,” Katz said. For example, in the Marine unit, second-quarter sales growth was driven by a higher mix of new premium lines in Bennington and Godfrey pontoons, the company said.
Polaris also has “disciplined quality assurance protocols and well-developed manufacturing processes,” Katz said. She expects Polaris to devote 4.5% of sales to R&D over the next five years, up from 4.3% on average over the last decade.
That should mean success ahead. “When consumers replace or think about purchasing products in the snowmobile and off-road categories, they want the best products with the newest technology, which is what Polaris provides,” Katz said.
As for market share, over the past decade, Polaris has enjoyed a No. 1 U.S. share of 30% in the ATV sector, according to Powersports Business and Morningstar. In snowmobiles, Polaris has grabbed more than 30% of U.S. market-share, standing No. 2 after BRP’s (NASDAQ: DOO) Ski-Doo.
Buoyant earnings
Polaris reported strong earnings for the second quarter. Revenue rose 9% from a year earlier, and adjusted earnings per share jumped by almost 5 times. The operational gross profit margin climbed to 20% from 19.18%, thanks higher prices, lower promotion, and improved product mix.
But all of Polaris’ strengths haven’t done much for its stock in recent years. It generated negative annualized total returns of 13% for both the last year and the last five years.
Much of the company’s trouble has stemmed from a normalization of demand for powersports vehicles after the Covid pandemic. Recall that the pandemic, which sparked strong demand for recreation products, shriveled starting in 2022. The interest rate ascent of 2022-23 and its aftermath also put a crimp on demand for Polaris products. So did rising inflation.
But now things are looking up. Katz predicts the company will out-earn its cost of capital over the next 20 years.
So Polaris may be on the move.


Comments