



Ultra-luxury brands such as LVMH Moët Hennessy Louis Vuitton (CBOE: MC) and Hermes (CBOE: RMS) have struggled recently amid high inflation and sluggish economic growth overseas.
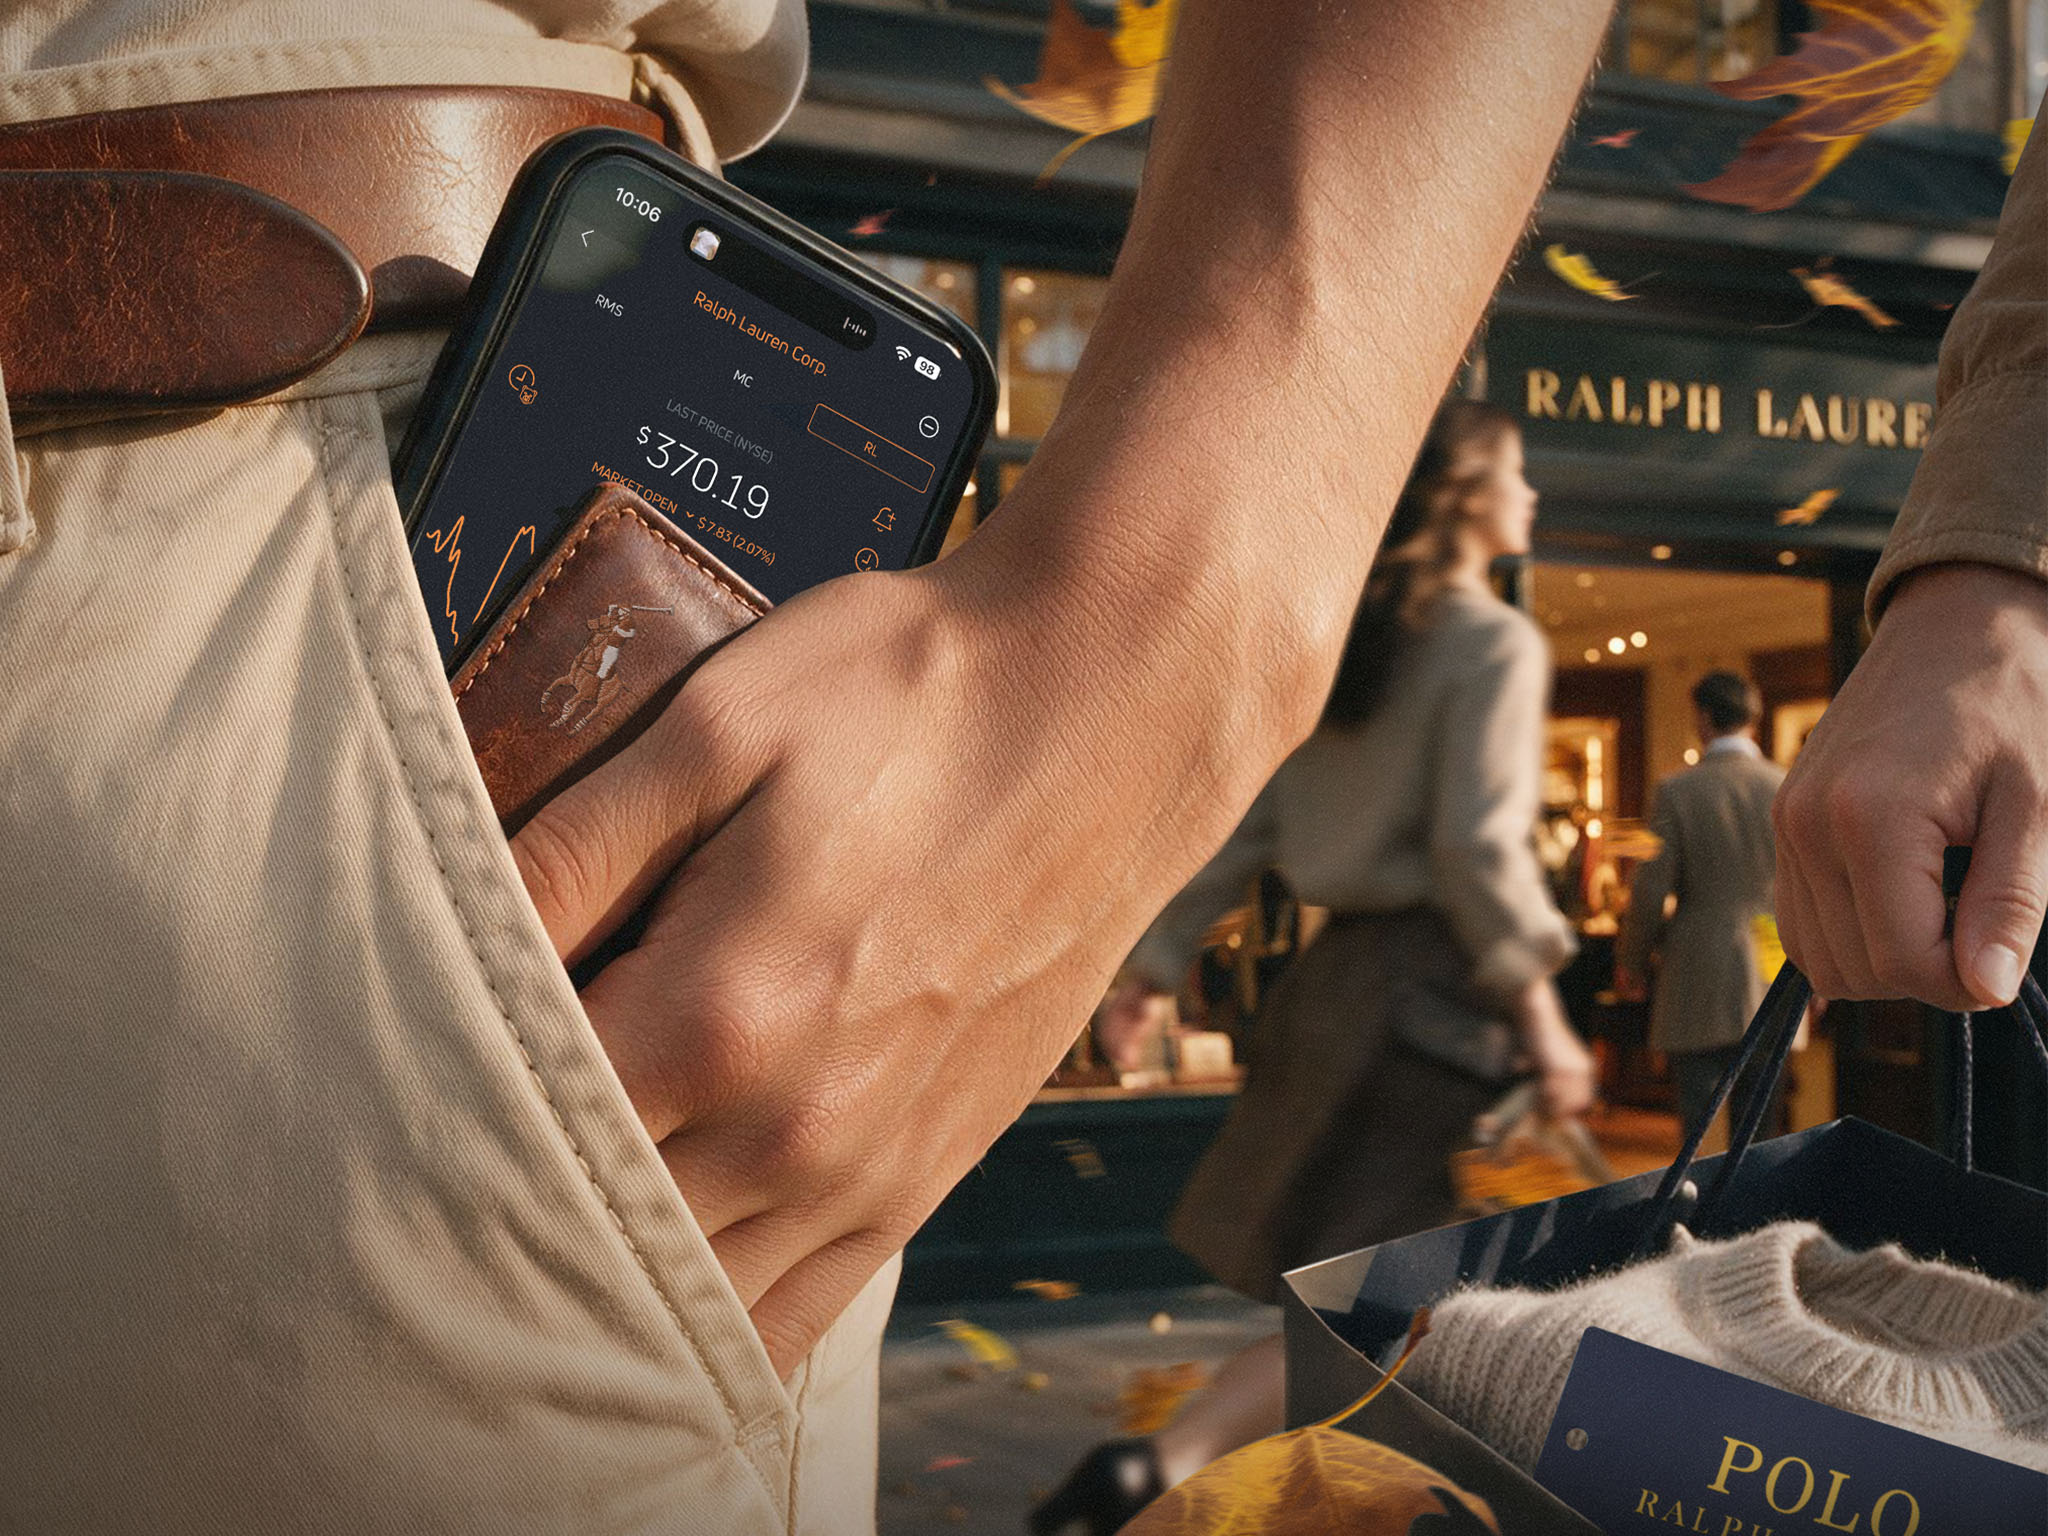
But many affordable luxury brands are doing just fine, as consumers are willing to shell out for the finer things in life at a lower price. Ralph Lauren (NYSE: RL), the almost 60-year-old icon of American upscale style, is a poster child for success. It’s best known for its classic polo shirt.
The company’s stock has generated annualized total returns of 32% over the past year, 50% over three years and 28% over five years. That easily beats the S&P 500 as well as LVMH and Hermes, which both have negative returns for one and three years.
Ralph Lauren is reaping the rewards of its post-Covid restructuring. Lax inventory control and frequent, deep discounting had plagued the company. So it shuttered underperforming stores, cut its reliance on U.S. department stores, curbed its own discounting and reduced product lead times.
Tasty profit margin
“These and other efforts have led to a significant gross profit margin increase,” Morningstar analyst David Swartz wrote in a report. Gross margin rose to 73.7% in the 2027 fiscal first quarter ended June 27 from 72.3% a year earlier.
To be sure, he forecasts the margin will dip to 68% by fiscal 2030 and then stay there for the next five years. “Competitive pressures in the affordable luxury space are likely to limit the firm’s ability to raise prices as much as it has in recent years,” he said. The company posted a 15% increase in average unit retail prices in the first quarter from a year ago.
Looking at geographies, 43% of Ralph Lauren’s revenue comes from North America, 31% from Europe and 24% from Asia. Analysts were impressed by the 25% surge for Asian sales in the first quarter.
China sales have jumped to 10% of the total from only 3% before the pandemic. And Swartz sees more room for gains, given the strong appeal of luxury goods for Chinese consumers.
The women’s market also represents an opportunity for Ralph Lauren, Dana Telsey, founder of consumer research firm Telsey Advisory Group, told Barron’s. The women’s department now provides just 30% of Ralph Lauren’s sales. That translates to a mere 1% market share for women’s apparel and accessories.
Marketing, direct to consumer
Analysts appreciate the company’s marketing efforts, which have buttressed the strength of its brands. Ralph Lauren allocated 7.8% of sales to marketing and advertising in fiscal 2026, up from 4.5% in 2020.
The company is devoting more of this spending to online events and social media, shifting from traditional ads, Swartz noted. The marketing also consists of new video displays in stores and remodeled selling spaces.
Meanwhile, Ralph Lauren added 6.5 million customers to its direct-to-consumer channel last year. “New customers are coming to the brand through full-price purchases. They are skewing younger, they’re less price sensitive, and more are female,” Tesley said.
It’s no wonder then that the company racked up a 14% revenue increase and a 22% earnings-per-share increase in the first quarter. Swartz projects its return on invested capital will rise to 22.5% over the next five years from 17% over the last five. Its cost of capital was 10% over that period.
So the polo pony in the logo that appears on Ralph Lauren clothes may be ready to charge.


Comments